
Searching for finance www disquantified .org can leave you wondering what the website offers and whether its articles are useful for everyday money decisions.
That is a reasonable question. When you are trying to manage bills, understand borrowing, or start saving, you need clear explanations and reliable information. A confident headline alone does not tell you whether the advice fits your circumstances.
This guide explains what you can find on Disquantified.org, how to assess its finance content, and which basic money principles are worth understanding before acting on any online article.
What Is Disquantified.org?
Disquantified.org publishes articles across several subjects. Its navigation includes Finance, Finance Advisor, and Investing, while its homepage also features content beyond finance.
The phrase “finance www disquantified .org” appears to be a search query for the website’s financial content. It should not be treated as the name of a separate financial product or investment service.
For readers, the useful starting point is the site’s Finance category. This provides a more focused route into its money-related coverage than browsing the general homepage.
What Does It Cover?
The Finance section includes articles about checking financial claims, identifying outdated information, evaluating sources, and finding money-related content. Other visible topics include crypto payment claims and investment administration.
Its Investing section also features articles about investment products and market themes.
That range makes it important to approach each article on its own merits. An accessible explanation of a financial term and an article discussing a particular investment require different levels of scrutiny.
Use the website to identify topics and questions, then verify any claim that could influence a financial decision.
How to Judge Its Reliability
A website’s appearance cannot establish whether its financial guidance is accurate. The more useful questions concern the person writing the article, the evidence supporting it, and the limits it acknowledges.
Look for an identifiable author and relevant, verifiable experience. A title such as “advisor” does not, by itself, establish professional registration or qualifications.
Next, examine the sources. Does the article link to original research, official guidance, or the financial provider’s actual terms? Can you trace a statistic to its origin?
Check the publication date as well. An older explanation of budgeting may still be useful, while an old statement about interest rates, taxes, or account fees may need updating.
Finally, look for commercial disclosures. Sponsored content and affiliate links do not automatically make an article inaccurate, but readers should understand whether a recommendation has a financial incentive behind it.
The presence of finance articles does not establish that a publisher provides regulated financial advice.
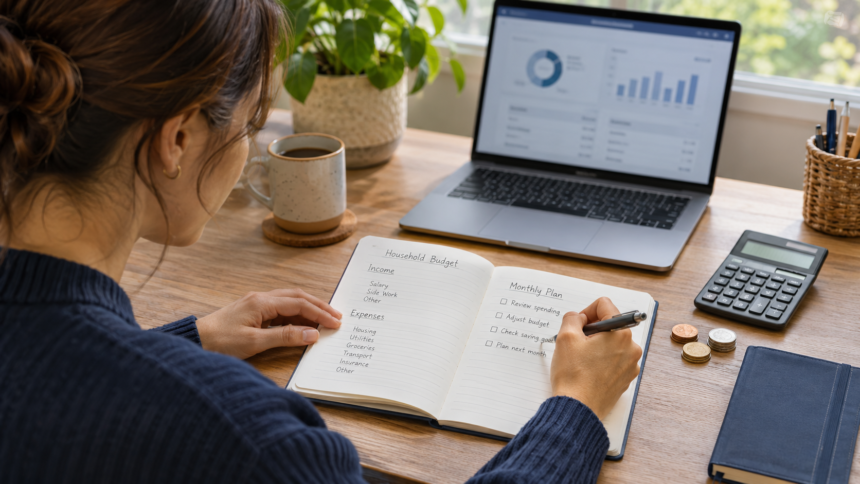
Start With Your Budget
Whatever website you use to learn about money, a budget gives the information a practical starting point.
Write down the income you actually receive and the expenses you must cover. Include housing, utilities, food, transport, debt payments, and less frequent bills that are easy to overlook.
For example, a yearly expense of $240 represents an average monthly cost of $20. Setting that amount aside regularly can make the eventual bill easier to manage. This is a simple planning illustration, not a required budgeting formula.
A useful budget should reflect your real circumstances. If almost all your income goes toward essentials, an ambitious savings target may be unrealistic. First identify what is fixed, what can change, and where the greatest pressure sits.
A workable budget gives you a clearer view of your choices.
Build Emergency Savings
An emergency fund is money reserved for unexpected expenses or a loss of income. Its purpose is to give you breathing room when an ordinary month becomes an expensive one.
The Consumer Financial Protection Bureau explains that the appropriate amount depends on your situation. Previous unexpected expenses can help you choose an initial target.
Start with an amount that feels achievable, then build it gradually. A modest reserve may help cover a repair or urgent bill without adding another borrowing commitment.
Keep emergency savings somewhere safe and accessible. Money needed at short notice serves a different purpose from money invested for a distant goal.
If you use the fund, rebuilding it becomes the next step. Using savings for a genuine emergency is exactly what the money is there for.
Understand Your Debt
Debt advice becomes more useful when you know the balance, interest rate, minimum payment, and due date for each account.
Two common repayment approaches are the highest-interest-rate method and the snowball method.
With the highest-interest-rate method, extra payments go toward the most expensive debt while you continue required payments on the others. This can reduce interest costs.
With the snowball method, extra payments go toward the smallest balance. Clearing an account sooner can provide motivation, although this approach may cost more overall.
Before following an article that recommends a new loan, examine the actual offer. Consider fees, repayment length, and total repayment costs alongside the monthly payment.
A smaller monthly payment can be helpful, but it does not necessarily mean the borrowing is cheaper.
Read Investment Claims Carefully
Investment content needs more scrutiny than a general explanation of saving or budgeting.
Before acting on an idea, establish what the investment does, how it could lose money, what it costs, and whether you can access your money when needed. Those questions matter more than an appealing return figure.
Fees deserve particular attention. Transaction charges, ongoing account costs, and product expenses can reduce the money you keep. The SEC’s Investor.gov encourages readers to review disclosures and compare costs before choosing an investment or professional.
Be equally careful with confident predictions. A projected return is an assumption about the future, not a promise.
If you cannot explain the main risks and costs in plain language, keep researching before committing money.
Check Advice Against Your Location
Online finance articles often reach readers in countries they were not written for.
An explanation may refer to a particular country’s tax system, retirement accounts, consumer protections, or professional registration rules. Those details may not apply where you live.
Check the relevant local regulator, tax authority, and provider documentation before using country-specific guidance.
For example, U.S. readers can use Investor.gov’s registration resources and FINRA’s BrokerCheck to research investment professionals. Readers elsewhere should use the appropriate official registers for their jurisdiction.
Matching information to your location is part of checking its accuracy.
Use What You Learn
The most useful result of reading a finance article is often one manageable action.
You might list your recurring expenses, check a loan’s fees, set an initial savings target, or read an investment’s official disclosure documents.
Avoid trying to overhaul every part of your finances at once. Choose the issue that matters most right now and gather the information needed to address it.
For someone facing expensive debt, that might mean comparing repayment approaches. For someone with unpredictable income, it might mean understanding essential monthly costs and building a cash reserve.
Financial education becomes valuable when it helps you make a clearer, better-informed decision.
FAQs
What does finance www disquantified .org mean?
It appears to be a search phrase referring to financial content on Disquantified.org. The website has Finance, Finance Advisor, and Investing categories.
Is Disquantified.org only about finance?
No. Its homepage also displays articles on other subjects. Readers interested specifically in money topics can begin with its finance-related categories.
Can beginners use its finance articles?
Beginners can explore topics through its articles, but should check definitions and important claims against authoritative sources. An article’s readability does not establish its accuracy.
Does the Finance Advisor category prove professional credentials?
No. A category label does not verify an author’s qualifications or registration. Check any claimed credentials independently before relying on someone for professional advice.
Should I invest based on a blog article?
A blog article can introduce an idea, but it should not be your only research. Review the investment’s official documents, risks, costs, and suitability for your circumstances.
How can I spot outdated financial information?
Check the publication and update dates, then verify time-sensitive details with the original source. Rates, fees, eligibility requirements, and tax rules deserve particular attention.
What should I learn first about personal finance?
Understanding your income, essential expenses, debt obligations, and savings needs provides a useful foundation. Your immediate priorities will depend on your circumstances.
Final Thoughts
When researching finance www disquantified .org, start with a clear understanding of what you are reading: articles that need to be assessed individually.
Look for evidence, check dates, and distinguish general explanations from recommendations that could affect your money. A useful finance article should leave you better able to ask questions and understand your options.